Money stress and fun have an awkward relationship. When finances feel tight, enjoyment gets treated as a guilty extra. But life without any fun is a bad plan, and plenty of people overspend because they’ve gone too long without it.
The sensible middle is planning. You decide what’s worth spending on, find clever ways to enjoy it for less and know what to do if debt has grown bigger than your monthly budget can handle. This article takes those three steps in order.
Hosting at Home Without Losing Your Mind
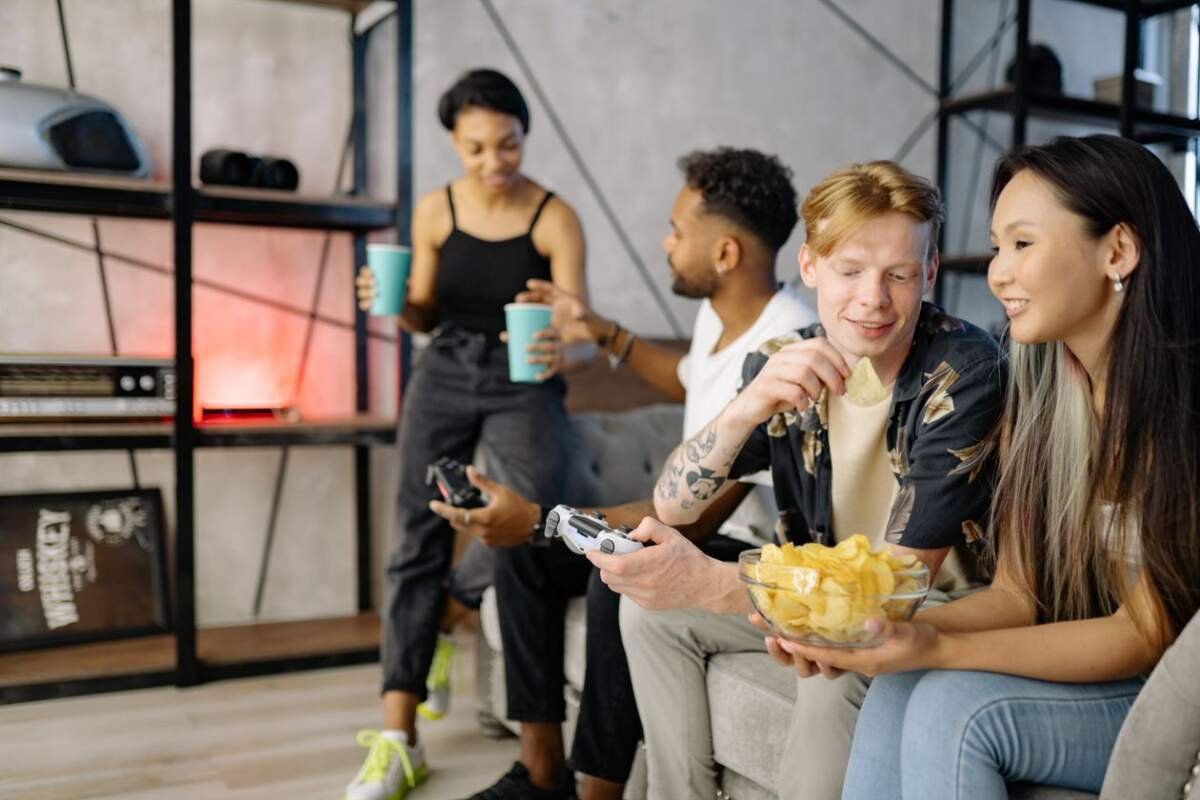
A party at home can be warmer, cheaper and more personal than renting a venue. It can also turn into a stressful weekend if you try to do everything yourself. The trick is to pick one or two things that make the event feel special and keep the rest simple.
Entertainment is a good place to put some budget. Guests love something interactive, and many hosts book photobooth services so people have something to do together and leave with a keepsake. It’s one example of how smart event planning at home can keep the fun high and the stress low.
A few planning habits that save money and sanity:
- Set a total budget first, then split it by category
- Cook or buy a few dishes well instead of ten dishes badly
- Send invitations early so you can plan quantities properly
- Ask friends to bring a dish or a drink, since most people like to help
- Make a simple timeline for the day, including setup and cleanup
- Keep a small buffer for last-minute surprises
- Choose a theme that uses things you already own
I noticed at one gathering that the host spent very little and everyone raved about it. She’d picked a single focus, good music and plenty of seating, and ignored the rest.
Cheaper Leisure Is a Skill
Entertainment doesn’t have to cost much, but it does take creativity. Travel, concerts and dinners out add up quickly. A budget-friendly rhythm usually mixes small paid treats with free or cheap alternatives.
Whether you’re searching for the best financial advisor to help you sort out the bigger picture or simply trying to spend less on leisure, one idea worth a look is virtual reality, which lets you visit places and try experiences from your living room.
The same logic applies to ordinary weeks. Library cards, free community events, potluck dinners, a long walk with a thermos and board games with friends all cost almost nothing. The trick is to schedule them, because unplanned evenings default to the most expensive option, which is usually takeout and a streaming subscription.
A word on advisors: there isn’t a single “best” one for everyone. The right fit depends on your situation, your goals and how they charge. Look at credentials, fees, conflicts of interest and whether they work with people in your circumstances. Ask them to explain how they’re paid in plain language.
When Money Stress Is Bigger Than the Party
Sometimes the problem isn’t the entertainment budget. It’s debt that keeps growing, with minimum payments barely touching the balance. If that sounds familiar, the first thing to know is that you have more options than most people realize, and that waiting usually makes things worse.
In Canada, one formal option is a consumer proposal. It’s an arrangement, set up through a Licensed Insolvency Trustee, where you offer creditors a repayment plan they vote on. The benefits of a consumer proposal are worth understanding if debt feels unmanageable: people commonly use it to settle what they owe in a structured way and regain some financial clarity, and it generally pauses collection actions once filed. It also has trade-offs, including an impact on your credit and fees built into the process, so it isn’t right for everyone.
The emotional side matters here as well. Many people wait far too long because of shame, and the delay lets interest and fees pile up. Debt is a very common problem, not a character flaw, and the people who deal with it every day have heard worse than yours.
This is general information, not financial or legal advice. A free initial consultation with a licensed professional is a sensible way to learn what applies to your situation.
Debt Options at a Glance
Here’s a simplified comparison of common routes. Rules, costs and eligibility differ by country and by situation, so confirm details with a qualified professional.
| Option | How it generally works | Main upside | Main trade-off |
|---|---|---|---|
| Self-managed budget and repayment | You prioritize and pay down debts on your own | Full control, no formal process | Needs discipline and enough income |
| Credit counselling and debt management program | A non-profit agency negotiates one monthly payment | Simplified payments, interest often reduced | You typically repay the full balance |
| Consumer proposal (Canada) | A trustee files an offer to creditors | May reduce what you pay and give a clear plan | Credit impact and formal commitments |
| Bankruptcy | A legal process that can discharge many debts | A fresh start in serious cases | Longer credit impact and possible effect on assets |
Notice that the options run from light to heavy. Most people are better off starting at the gentler end and moving up only if needed.
How to Choose Help You Can Trust
Money trouble makes people vulnerable to bad deals. A few checks protect you:
- Confirm that the professional is licensed in your region
- Ask for a clear explanation of all fees before you agree to anything
- Be wary of anyone promising to erase debt quickly or guaranteeing results
- Get a second opinion on any major decision
- Read every document, and ask questions about what you don’t follow
- Keep copies of everything you sign
If something feels rushed or too good to be true, slow down. Legitimate professionals don’t mind questions.
Make Fun and Finances Work Together
The goal isn’t to choose between enjoying life and being responsible. It’s to build a system that does both. A simple monthly rhythm helps:
→ Week one: list fixed bills and set aside savings first
→ Week two: decide the fun budget and plan one event or outing
→ Week three: review spending and adjust
→ Week four: check debts, balances and progress
When you plan fun in advance, it stops being a guilty impulse and becomes a normal part of the month. And if debt is pressing, taking one concrete step, such as booking a consultation, can lift a surprising weight off your shoulders.
Conclusion
A good financial life has room for joy and a plan for trouble. Host smart, find cheaper ways to enjoy your time and learn your debt options before stress forces your hand. Small, steady decisions beat panicked ones, and most of them cost nothing but attention.